VA Loans in Texas: Guidance From Application to Closing
You’ve served…Now let us serve you.
VA home loans offer powerful financing benefits for eligible veterans, active-duty service members and surviving spouses. As a VA Loan Specialist, I help borrowers understand their eligibility, entitlement and financing options so they can make confident decisions from pre-approval through closing.
What is a va home loan?
A VA home loan is a mortgage backed by the U.S. Department of Veterans Affairs for eligible veterans, active-duty service members and certain surviving spouses. VA loans can offer significant benefits, including the possibility of 100% financing with no down payment, no monthly private mortgage insurance and flexible qualification guidelines. Eligibility and loan approval requirements still apply.n?
Why Consider a VA Loan?
0% Down Payment Potential
Eligible borrowers may be able to finance 100% of the home’s purchase price, subject to VA and lender requirements.
No Monthly PMI
VA loans don’t require traditional monthly private mortgage insurance, which can help reduce the monthly housing expense compared with some low-down-payment alternatives.
Competitive Financing
VA-backed mortgages can offer attractive rates and flexible qualification guidelines for eligible borrowers.
Reusable Benefit
VA home loan eligibility isn’t necessarily a one-time benefit. Depending on entitlement and circumstances, eligible borrowers may use their VA benefit more than once.
Who May Be Eligible for a VA Loan?
VA loan eligibility is generally based on military service history and is documented through a Certificate of Eligibility (COE). Veterans, active-duty service members, certain National Guard and Reserve members, and some surviving spouses may qualify.
What Is a Certificate of Eligibility?
Your COE tells the lender that you meet the VA’s service requirements and provides information about your available entitlement. In many cases, your lender can obtain the COE electronically during the loan process.
VA Loan Credit, Income and Qualification
Credit Score
The VA does not establish a universal minimum credit score for its home loan guaranty. Individual lenders may establish credit requirements, and your overall credit profile is considered as part of the underwriting process.
Debt-to-Income (DTI) Ratio
Debt-to-income ratio is NOT part of VA loan qualification, but it isn’t evaluated in isolation. However, income, credit history, assets, housing expenses and residual income may all factor into the underwriting decision.
Residual Income
VA underwriting places particular emphasis on residual income—the money remaining each month after major obligations and estimated living expenses. Required residual income varies based on factors such as household size, loan amount and geographic region.
Patti Jo’s Guide
This is where having a VA Specialist matters. Majority of all mortgage companies have “overlays” on top of the VA Guidelines. This means they have additional rules/guidelines put on top of the VA Guidelines. While the VA does NOT mandate a DTI maximum threshold, mortgage lenders/brokers will put one on the program. We do not. 88.989% is the highest DTI ratio I have closed a loan on. This is where the Residual Income comes in. In this example, my borrower’s housing ratio was around 50.00% and had $1,500 residual income (he needed to have at least $900) and my client received an automatic approval in the underwriting system. So while you may be denied with one lender, do not give up and find a lender (or just ask me!) that does not have overlays.
Understanding the VA Funding Fee
Most VA borrowers pay a one-time VA funding fee that helps support the VA home loan program. The amount can vary depending on factors such as down payment, whether you’ve used your VA benefit before and the type of VA transaction.
Who May Be Exempt From the VA Funding Fee?
Certain borrowers may be exempt from paying the VA funding fee, including some veterans receiving qualifying VA disability compensation and certain eligible surviving spouses. Your Certificate of Eligibility and VA documentation can help determine whether an exemption applies.
VA Loan Closing Costs and Seller Contributions
A zero-down-payment VA loan doesn’t necessarily mean zero cash needed at closing. Buyers may still have closing costs, prepaid taxes and insurance, and other transaction expenses. Depending on the transaction, seller-paid costs, lender credits or other allowable sources may help reduce the amount the buyer needs at closing.
Patti Jo’s Guide
I encourage VA buyers to understand the entire cash-to-close picture—not just the down payment. Before you make an offer, we’ll review the estimated payment, closing costs, prepaid expenses and available strategies together.
How the VA Loan
Process Works
Confirm Eligibility
We review your goals and obtain or verify your Certificate of Eligibility.
Get Pre-Approved
We’ll review income, assets, credit and your overall financing profile.
Find Your Home
You’ll shop with a clearer understanding of your financing and estimated payment.
VA Appraisal & Underwriting
The property and loan are reviewed to make sure applicable VA and lender requirements are met.
Closing
After final approval, you’ll sign your closing documents and complete your home purchase.
Using a VA Loan to Buy a Home in Texas
Texas offers veterans and military families a wide range of housing markets, but property taxes, homeowners insurance, HOA costs and location can significantly affect the monthly payment—even when two homes have similar purchase prices.
Patti Jo’s Guide
I work with VA borrowers throughout Texas, including buyers in Rockwall County and communities such as Rockwall, Heath, Fate and Royse City. My goal is to help you understand the complete financing picture before you make an offer. And if you have a 100% disability rating, here in Texas, you pay zero property taxes!
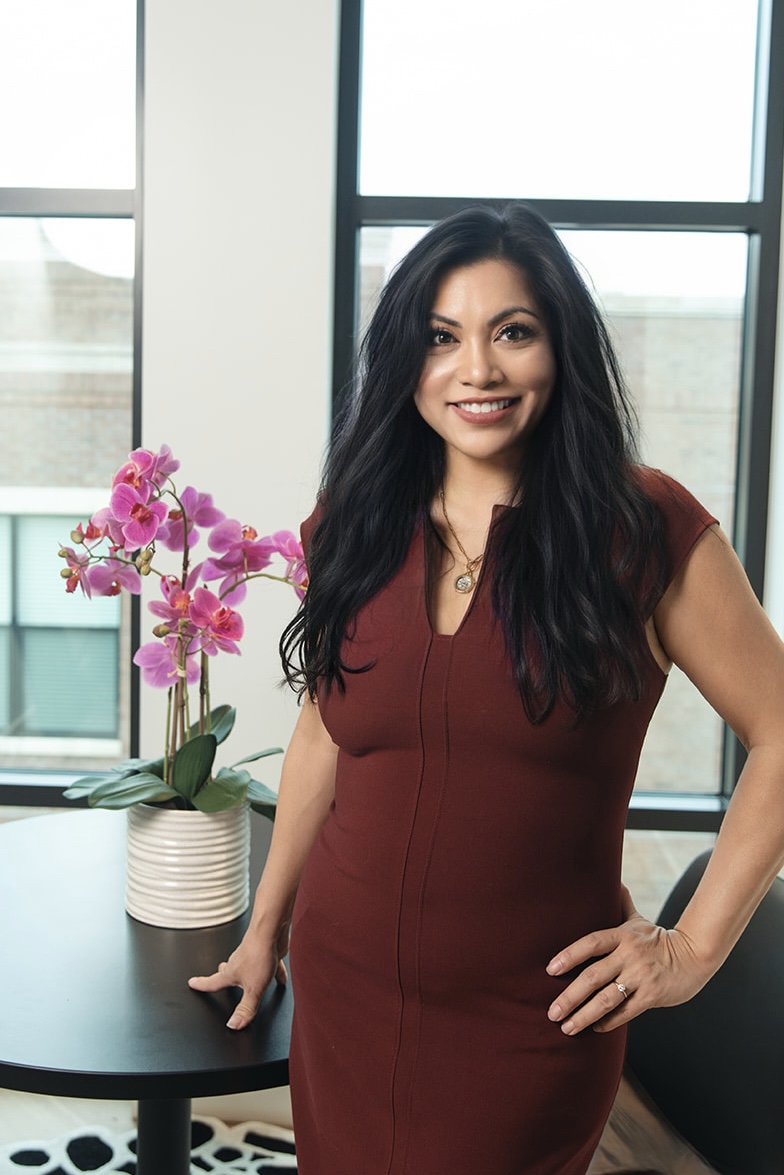
Patti Jo “PJ” Hollon, CMA
Work With a VA Loan Specialist
VA financing has rules and opportunities that aren’t always obvious from an online mortgage calculator. I believe veterans deserve to understand how their benefit works—not simply be handed a rate and payment.
I’m Patti Jo Hollon, a mortgage lender, Certified Mortgage Advisor and VA Loan Specialist serving borrowers throughout Texas. My approach is straightforward: explain the options, show you the numbers and help you make the decision that fits your goals and plan when the time will be right in the future to do a VA IRRRL and continue to get/keep your payments.
Remember…You’re More Than Just a Rate
So Don’t Shop for a Rate…
Shop for a Guide!
Ready to Explore Your
VA Loan Options?
Whether you’re using your VA benefit for the first time or you’ve purchased with a VA loan before, let’s look at your eligibility, financing options and next steps.